RENT OR BUY?
Rent vs Buy
Calculator
Compare the estimated financial impact of renting versus buying a home.
A mortgage payment is only part of the picture. This calculator helps you compare rent, ownership costs, potential equity and how long you expect to stay so you can make a more informed decision.
COMPARE RENT VS BUYTHE REAL QUESTION
Which Option Makes
More Sense for You?
Renting may offer flexibility and lower upfront costs. Buying may provide stability, equity and long-term financial benefits.
LOOK AT THE FULL PICTURE
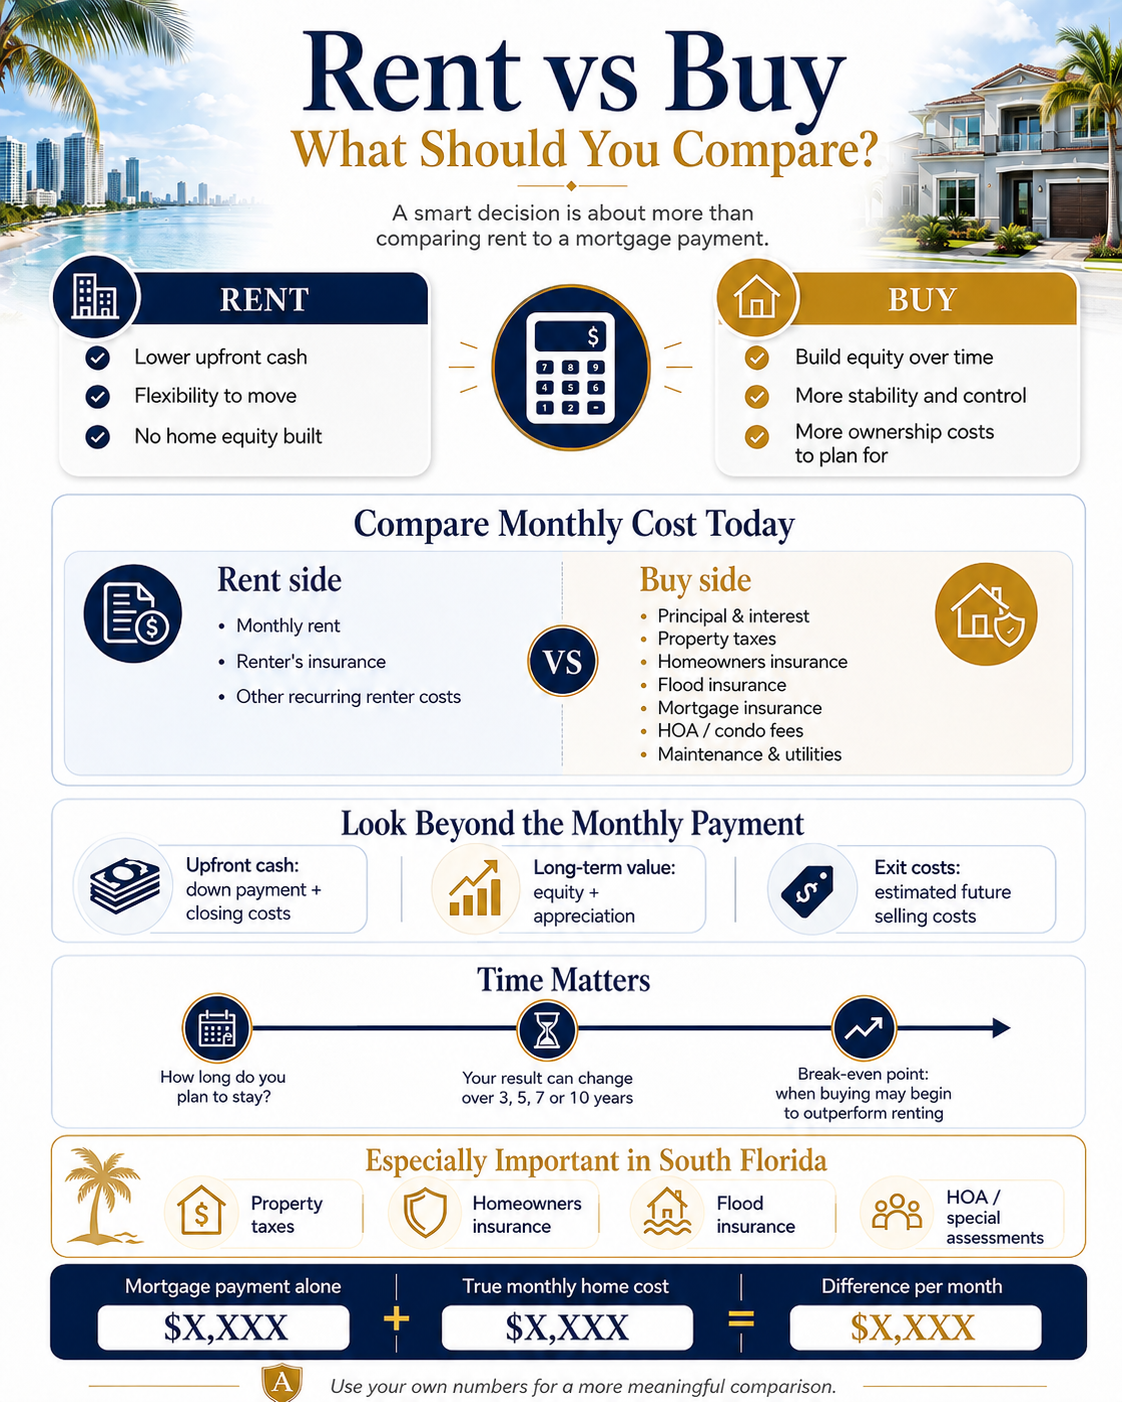
Rent vs Buy Is About
More Than the Payment.
Comparing monthly rent to a mortgage payment alone does not tell the whole story.
Renting and owning come with very different upfront costs, ongoing expenses and long-term financial outcomes. The right comparison should consider what each option costs today and what may happen over the years you expect to stay.
Monthly Cost
Compare rent with the complete estimated monthly cost of owning.
Upfront Cash
Consider down payment, closing costs and other money required to purchase.
Long-Term Value
Estimate equity, appreciation, rent increases and the financial effect of time.
Break-Even Point
See approximately when buying may begin to create a stronger estimated financial position.
A SMARTER WAY TO LOOK AT HOMEOWNERSHIP
Think investment first.
When you move in, it becomes your home.
RUN YOUR NUMBERS
Compare Renting
With Buying.
Enter a realistic rental scenario and a potential home purchase. We’ll compare the estimated monthly costs, upfront cash, long-term equity and investment impact of each option.
YOUR ESTIMATED COMPARISON
Rent vs Buy Results
Based on the assumptions you entered.
MONTHLY COST TODAY
What Does Each Option Cost Right Now?
Enter your information and calculate to compare the two options.
PURCHASE DETAILS
Financing & Upfront Cash
OWNERSHIP POSITION
Estimated Value at the End of Your Time Horizon
RENTER INVESTMENT POSITION
What Could the Renter’s Available Cash Become?
CASH FLOW OVER TIME
Estimated Total Housing Cash Outlay
ESTIMATED LONG-TERM FINANCIAL POSITION
Estimated net ownership position
Estimated renter investment position
Your long-term comparison will appear here.
ESTIMATED BREAK-EVEN POINT
—We’ll calculate the comparison month by month and estimate when buying may begin to produce a stronger financial position than renting.
WHAT THE NUMBERS SUGGEST
Your personalized comparison will appear here after you calculate.
This calculator provides estimates for educational and planning purposes only. Results depend on the values and assumptions entered and do not predict future real estate values, investment performance, taxes, insurance costs, financing terms or market conditions. Home appreciation is an assumption and is not guaranteed. This tool is not financial, tax, legal, lending or investment advice.
MORE THAN A MONTHLY PAYMENT
Renting vs. Owning
Is About More Than Money.
The calculator helps compare the financial side, but your home also affects your freedom, stability, lifestyle and long-term goals.
Pay Yourself First.
When homeownership fits your finances and your plans, part of your mortgage payment can reduce what you owe and build equity in an asset you own.
Rent gives you a place to live and valuable flexibility, but your monthly rent does not create ownership in the property.
BUYING
The Benefits of Ownership
PROS
- Build Equity A portion of your mortgage payment may reduce your loan balance and increase your ownership in the property.
- Potential Appreciation If the property increases in value, that appreciation may contribute to your long-term financial position.
- More Control Make improvements, renovate, decorate and personalize your home without a landlord’s approval.
- Greater Housing Stability You are not dependent on a landlord deciding whether to renew your lease or sell the property.
- Fixed Mortgage Principal & Interest With a fixed-rate mortgage, principal and interest payments remain predictable even though taxes, insurance and other ownership costs may change.
- An Asset You Can Keep A home can become a long-term asset that may eventually be owned without a mortgage.
CONS
- Higher Upfront Costs Down payment, closing costs and initial repairs can require significant cash.
- Maintenance Is Yours Repairs, appliances, roofs, HVAC systems and unexpected expenses become your responsibility.
- Taxes & Insurance Can Rise Property taxes, homeowners insurance, flood insurance and association costs may change.
- Less Short-Term Flexibility Buying and selling takes time and involves transaction costs.
- Property Values Can Change Appreciation is never guaranteed and real estate markets can rise or fall.
RENTING
The Benefits of Renting
PROS
- Greater Flexibility Renting can make it easier to relocate for work, family, lifestyle or other opportunities.
- Lower Upfront Commitment You may need substantially less cash upfront than you would for a home purchase.
- Fewer Repair Responsibilities Major property repairs are generally the landlord’s responsibility.
- Useful for Shorter Time Horizons Renting can make sense when you are unsure where you want to live long term.
- No Property Market Exposure You are not directly exposed to changes in the property’s resale value.
CONS
- No Ownership Equity Your rent pays for the use of the property, but it does not give you an ownership interest.
- Rent Can Increase Your housing cost may increase each time your lease is renewed.
- Limited Control Renovations, pets, decorating and other changes may require landlord approval.
- Your Lease May Not Be Renewed The owner may decide to sell, move into the home or change how the property is used.
- You Do Not Participate in Appreciation If the property increases substantially in value, that increase belongs to the property owner.
If you are going to spend thousands of dollars every month on housing, it is worth asking whether some of that money could be working toward something you own.
Buying is not automatically better than renting. The right decision depends on your finances, how long you expect to stay, the property you choose and what matters most to you.
RUN YOUR COMPARISONWHICH PATH FITS YOU?
The Right Decision
Depends on Your Life.
The numbers matter, but so do your plans. How long you expect to stay, your financial readiness, your need for flexibility and the kind of lifestyle you want can all influence the right choice.
BUYING MAY FIT YOU IF…
You Are Ready to Put Down Roots.
- You expect to remain in the area for several years.
- You have the cash needed for a down payment, closing costs and reserves.
- Your monthly budget can comfortably handle the full cost of ownership.
- You want the opportunity to build equity and participate in future appreciation.
- You value control over your property, renovations and living environment.
- You are comfortable accepting responsibility for maintenance and unexpected repairs.
RENTING MAY FIT YOU IF…
Flexibility Matters More Right Now.
- You may relocate within the next few years.
- You are still deciding where you want to live long term.
- You want to preserve cash rather than use it for a down payment and closing costs.
- Your current rental cost is significantly lower than comparable ownership costs.
- You do not want responsibility for major repairs and property maintenance.
- Your financial position is not yet where you want it to be before purchasing.
BEFORE YOU DECIDE
Ask Yourself These Five Questions.
How long do I realistically expect to stay in this home?
Can I comfortably afford the complete monthly cost of ownership?
Will I still have adequate savings after the purchase?
How important are flexibility and the ability to move quickly?
Do I want my housing dollars helping build an asset I own?
READY TO LOOK AT THE REAL OPTIONS?
The Calculator Gives You Numbers.
We Help You Make the Decision.
Rent vs. buy is different for every person and every property. We can help you compare what you are paying now with actual homes available in the market and determine what makes sense for your goals.
THE ACHIEVE APPROACH
PAY YOURSELF FIRST.
If ownership fits your finances, your lifestyle and your time horizon, your housing payment may also help build something you own.
The goal is not simply to buy a home. The goal is to make a smart real estate decision.
THE ACHIEVE TEAM · MLS PROPERTY DISCOVERY
Compare Available Homes and Rentals
After calculating rent versus buy, explore both markets with current MLS searches.
Property cards are served from the AchieveMLS Search website and include listing-broker attribution. Select a listing to view its full details and return to this Achieve page.